Infrastructure & Security · Oct 2, 2026
Micron beats estimates with $54.2 billion in revenue and an 87% gross margin; memory shortage seen lasting into 2028, but shares fall
More than 75% of fiscal 2027 shipments are already allocated or under contract. It is the most reliable hard figure yet on the strength of AI capital spending, but the market is now pricing whether the shortage will continue.
Seiichi Tanaka · Editor-in-Chief
Key points
- According to the earnings release filed with the SEC (a primary source), revenue was $54.2 billion and gross margin was 87%. More than 75% of fiscal 2027 shipments are already allocated or under contract
- Demand is no longer in doubt. The figures show the strength of AI capital spending through signed contracts, not forecasts
- Even so, Micron shares fell about 3% and Western Digital also declined, 247 Wall St. reported. The market's question has shifted from how strong demand is now to when the shortage will end
Micron reported results for the fourth quarter of fiscal 2026 after the U.S. market close on September 30. According to the earnings release filed with the SEC (exhibit to Form 8-K, primary source), revenue was $54.2 billion and gross margin was 87%. The company said more than 75% of the units it will ship in fiscal 2027 are already allocated or under contract. It expects the memory shortage to last into 2028.
These are hard numbers on the strength of AI capital spending. They come from contracts and reported earnings, not from forecasts or interviews. Yet the stock fell the next day. That both things happened together is the most important takeaway in infrastructure this week.
The results: margins unlike a memory company's
Investing.com reported that Micron beat fourth-quarter estimates on AI-driven demand and gave a strong outlook for fiscal 2027 (Investing.com). 247 Wall St. also wrote that it was a record quarter and that guidance for the next quarter came in above consensus (247 Wall St.).
The figure that stands out most is the 87% gross margin. Memory was long a textbook commodity, with prices that swung sharply. Even in fiscal 2018, the peak of the previous boom, Micron's gross margin was around 60%. A margin of 87% is a software company's level. AI demand for HBM (high-bandwidth memory) has outrun supply, and pricing power has clearly shifted to sellers.
What "more than 75% allocated" means
More telling than the guidance is that more than 75% of fiscal 2027 shipments are already allocated or under contract. That means hyperscalers and GPU makers are locking in memory now for supply more than a year out. Bullish comments can be walked back. Contracts are much harder to cancel.
The figures line up with what AI labs did this week. Anthropic's Sonnet 5.5 and OpenAI's GPT-6.1 Sol are now priced the same, at $2 per million input tokens and $10 per million output tokens. On September 22, Opus 5.5 cut its cache-read price by 60%. According to Epoch AI, the cost of reaching a given level of performance is falling about 47% per quarter. As token prices drop, agent-style workloads that keep long contexts running become more common, and consumption has grown enough to earn the name Tokenmaxxing. The cost of those price cuts shows up as demand for the memory that runs the models. Token prices keep falling while memory prices rise. The numbers suggest AI profits are starting to pool in this layer.
Shares still fell
According to 247 Wall St., Micron shares fell about 3% despite a record quarter and above-consensus guidance (as reported). Western Digital also declined the same day, and SK hynix drifted without clear direction, the outlet said. South Korea's SBS also reported on what Micron's results could mean for the country's two memory makers (SBS).
Neither the company nor news reports have pinned the decline on a single reason. Still, the numbers suggest a few. First, an 87% gross margin leaves little room for further gains. Second, if more than 75% of shipments are already under contract, prices for that future supply are already set, which limits how much Micron can gain if prices keep rising. Third, the "into 2028" outlook can be read as the company itself saying the shortage has an end date. The financial backdrop is also hard on richly valued stocks: the 10-year Treasury yield is above 5%, and investors are weighing a possible rate hike at the October 28 FOMC meeting.
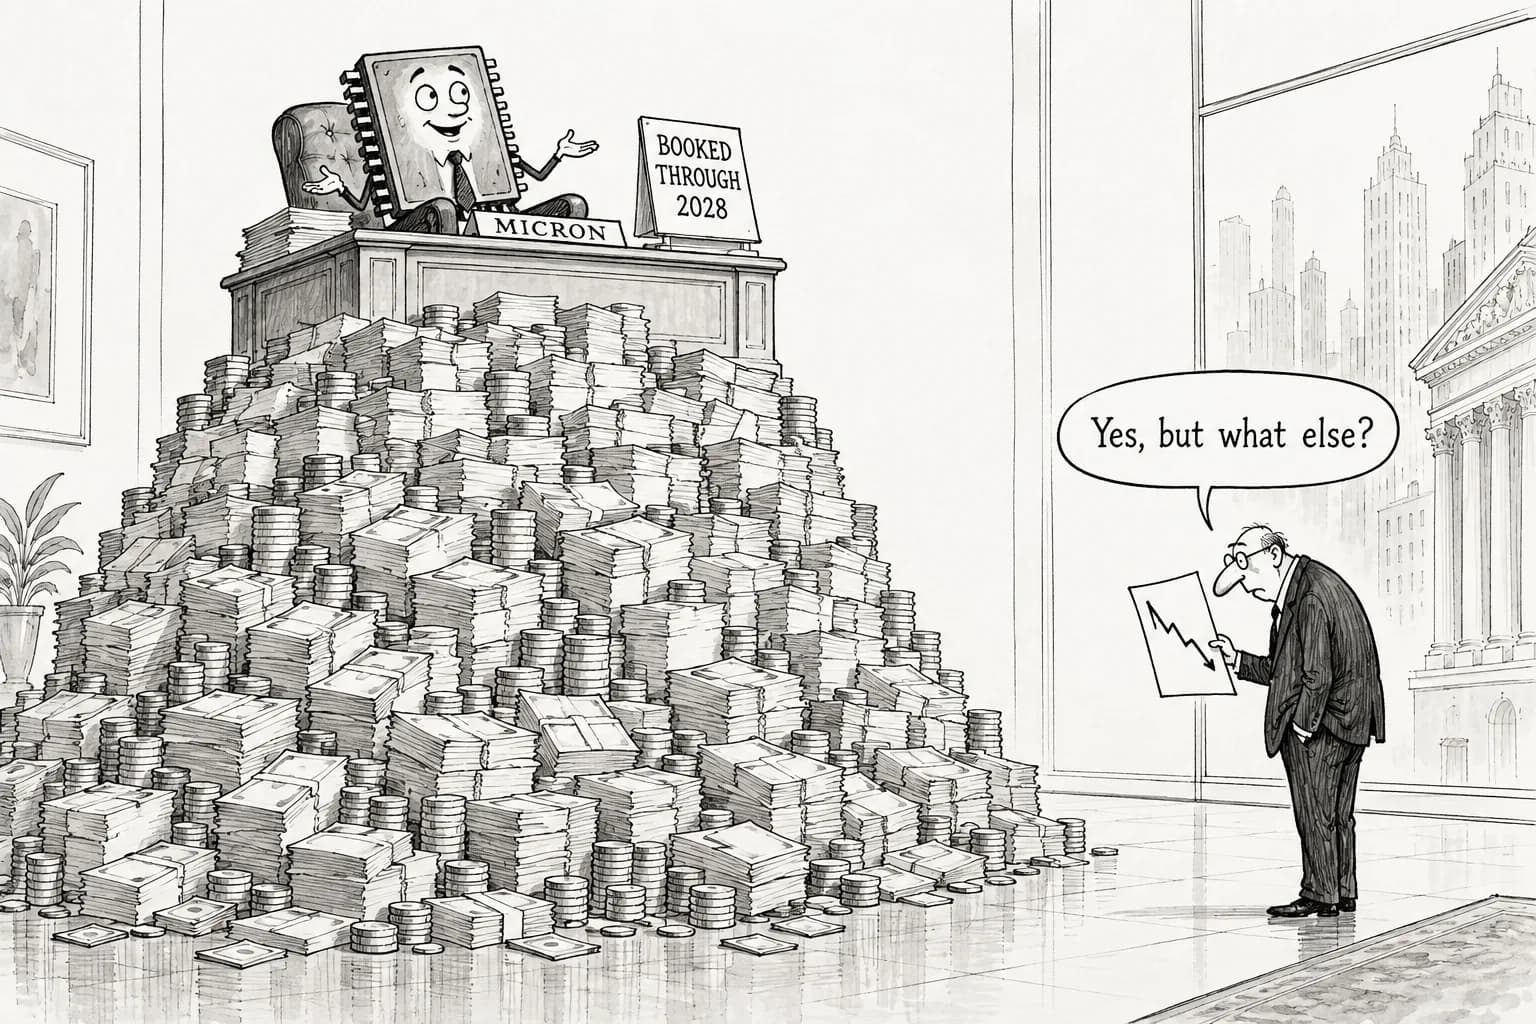
The market no longer questions how strong demand is today. What it is pricing now is whether the shortage will last beyond 2028, and how far the 87% margin will fall once memory makers' added capacity catches up.
A yardstick for AI capital spending
Until now, the strength of AI capital spending has mostly been measured by hyperscalers' investment plans and reported deal values. Reported valuations and contract values have sometimes differed sharply from reality. Micron's figures, by contrast, come from audited results filed with the SEC and the share of shipments under contract. For now, they are the most reliable measure of demand.
By that measure, demand is largely spoken for through fiscal 2027. The market's reaction shows investors are already looking at the year after. The question in AI infrastructure is starting to shift from whether demand exists to when the shortage will ease. The next things to watch are whether Samsung's and SK hynix's results show the same contract picture, and how much their capacity expansion plans shorten the 2028 outlook.
Editorial cartoon
Sources
- https://www.sec.gov/Archives/edgar/data/0000723125/000072312526000018/a2026q4ex991-pressrelease.htm
- https://www.investing.com/news/earnings/micron-beats-q4-estimates-on-aifueled-demand-gives-strong-fiscal-2027-outlook-4925841
- https://247wallst.com/investing/2026/10/01/micron-slips-3-despite-record-quarter-and-above-consensus-guidance-western-digital-dips-sk-hynix-drifts/
- https://news.sbs.co.kr/english/article.do?news_id=N1008779185