Money · Oct 15, 2026
CoreWeave bonds at 15% and CPI at 3.7% collide, and AI borrowers sell off together: CoreWeave −16%, Oracle −10%, Fink says 'new financing vehicles for compute are essential'
The day the 'capital is the constraint' line that bankers had been saying out loud became the price of neoclouds, Oracle and power stocks
Koji Yamamoto · Economics Analyst
Key points
- September CPI rose 3.7% year on year and Treasury yields climbed. The assumption that rates would not fall hit AI borrowers' financing directly
- CoreWeave's bond yield was reported to have reached 15%, and the stock fell 16%. Oracle fell 10%, and neoclouds and power stocks were sold off alongside them
- BlackRock's Fink said 'the need to create new financing vehicles for compute is essential', and Gartner estimated that over $3.5 trillion of AI infrastructure spending could be exposed to impairment by the end of 2030
In the US market on October 14, companies that have borrowed to fund AI were sold off together. The trigger was two numbers landing on the same day. The September consumer price index (CPI), released in the morning, rose 3.7% from a year earlier, and Treasury yields climbed. The same day, the yield on bonds issued by AI cloud provider CoreWeave was reported to have reached 15%, and the stock fell 16%. Oracle also fell 10%, with neocloud peers and power stocks reportedly following.
Until the day before, US bank executives had been saying out loud that 'capital is what constrains AI capital spending'. October 14 was the day those words became a market price.
A hot CPI broke the assumption AI borrowers were counting on
The September CPI published by the Bureau of Labor Statistics (BLS) rose 3.7% from a year earlier (BLS release, primary source). According to CNBC, Treasury yields rose on the number and the outlook for rate cuts was reportedly pushed further out (CNBC).
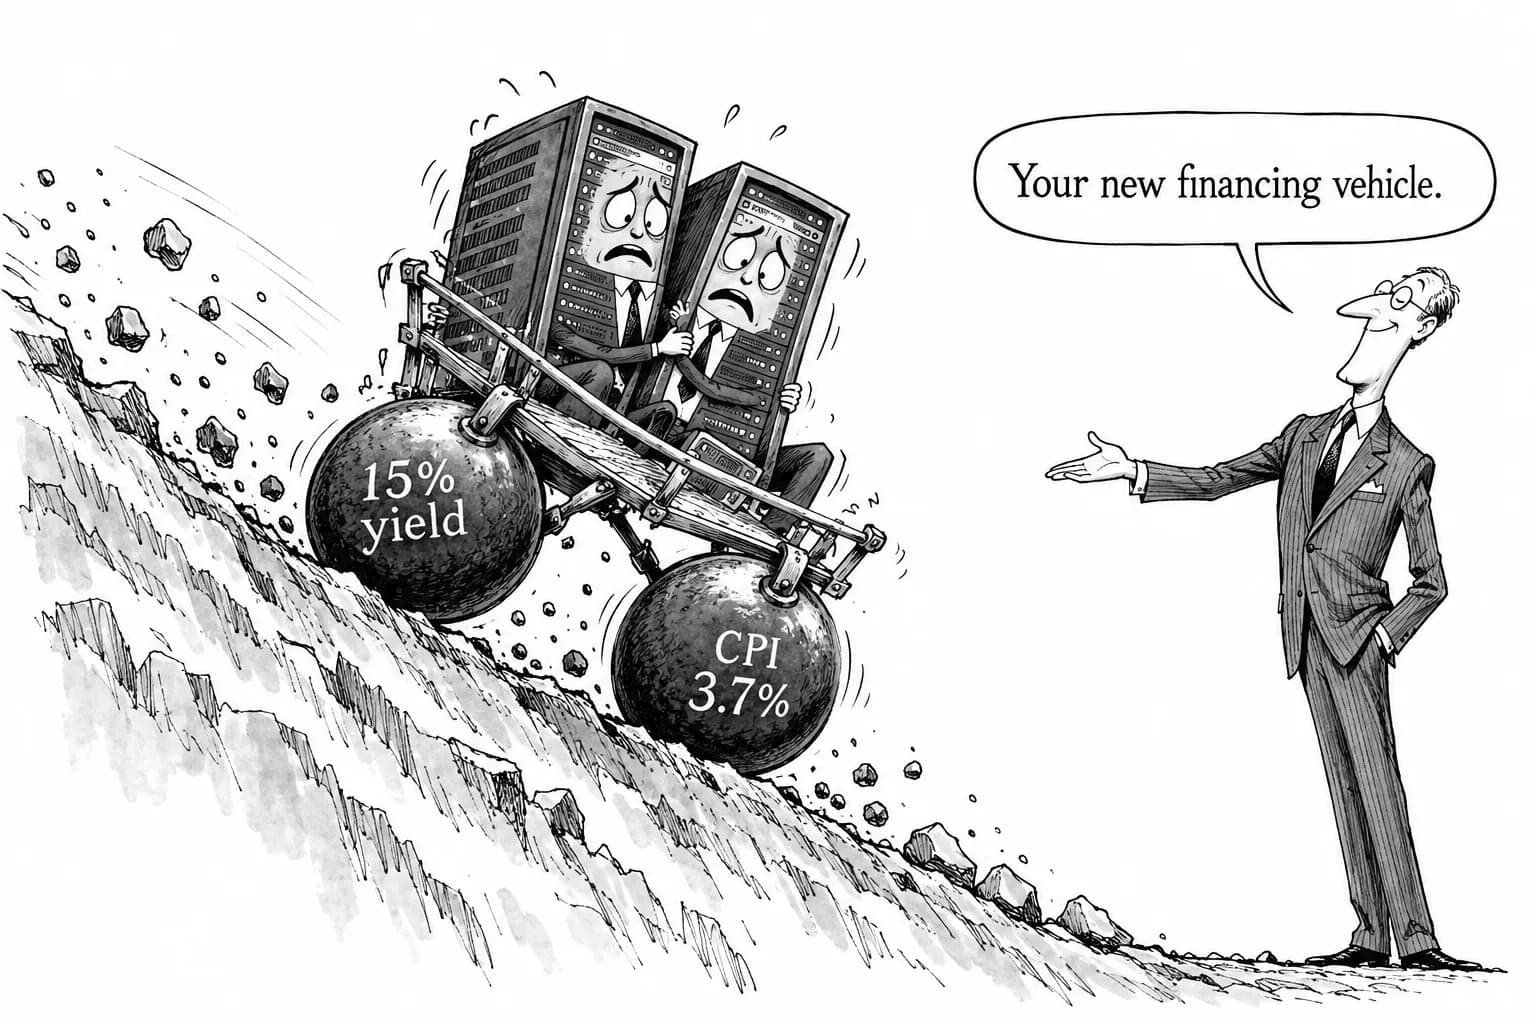
For AI borrowers, this is not just another economic indicator. The neocloud business runs on buying GPUs with debt, leasing them out under multi-year contracts and using that revenue to repay the loans. If borrowing costs do not fall, and instead rise, the profit left over shrinks even when contract pricing stays the same. On the day the rate assumption collapsed, the most indebted companies were sold first, exactly as that structure would predict.
What a 15% bond yield means
Crypto Briefing and GuruFocus reported that the yield on CoreWeave's bonds reached 15% (Crypto Briefing, GuruFocus). When a bond's price falls and its yield rises, the market is repricing the risk that 'this company's debt might not come back'. A 15% level is not investment-grade territory. It is closer to a fire sale.
GuruFocus wrote that the selloff exposed the 'interest burden' of AI. Debt taken on to buy GPUs generates interest before the GPUs generate revenue. If the rate on new bond issues approaches 15%, buying the next batch of GPUs with debt becomes difficult in itself. CoreWeave's stock fell 16% because, working backward from the bond price, what is left for shareholders was reportedly cut down.
Chamath Palihapitiya posted about the yield on X, and SpaceX's Elon Musk replied with a single word. It is a short reply, but it is a record of one of the people putting the most capital into AI being startled by what borrowers are paying.
Yikes
Musk's own SpaceX is a company reportedly in the process of borrowing $40 billion. If AI borrowers are paying 15%, every company that raises money next will be measured by the same yardstick.
Who was sold
CoreWeave was not the only name sold. Oracle fell 10%. Oracle is building data centers for OpenAI with construction debt, and as previously reported, how that construction debt was selling had become the concrete example behind US banks' 'capital is the constraint' remarks. If CoreWeave's bonds trade at 15%, Oracle's construction debt gets looked at the same way.
Neocloud peers and the power stocks that sell electricity to data centers were reportedly sold on the same day. The drop in power stocks carries weight. Power companies are not AI borrowers. They are the AI borrowers' customers. They were sold anyway, likely because the market read it as 'if the borrowers cannot borrow, the data centers do not get built, and the electricity does not get sold'. The constraint on capital spread as a price down to the borrowers' downstream.
'Capital is the constraint', said out loud until the day before
As previously reported, US bank executives had been voicing the view that 'what constrains AI capital spending is not chips or power, but capital'. Until October 14, that was a line from earnings calls.
The same day, PitchBook reported that Volta had begun syndicating a $5 billion leveraged loan (PitchBook). The proceeds are for data center leases and GPU capital expenditures. On a day when CoreWeave's bonds trade at 15%, a $5 billion loan backed by the same kind of assets is being brought to market. Where those terms settle will be the first test of whether the banks' 'capital is the constraint' is true.
Markets Media reported that BlackRock's Larry Fink said there is a 'large opportunity' in the compute market (Markets Media). In the course of that, Fink is reported to have said the following.
The need to create new financing vehicles for compute is essential.
This is the world's largest asset manager acknowledging that 'the financing vehicles we have today are not enough'. Bank lending and bonds alone cannot keep capital up with the demand for compute. So new vehicles are needed, meaning structures that channel pension and insurance money directly into GPUs and data centers. Said the other way around, on the day CoreWeave's bond yield hit 15%, the rate at which companies can borrow through existing vehicles has reached a level that is no longer sustainable.
Gartner's $3.5 trillion is a number on the borrowers' side
On the same October 14, research firm Gartner issued a press release (Gartner, primary source).
Over US$3.5 trillion of artificial intelligence infrastructure spending could be exposed to impairment by the end of 2030.
Impairment is when a company admits that an asset it bought will not generate as much value as its book value and records the difference as a loss. The figure of over $3.5 trillion is an upper-bound estimate of the share of AI infrastructure spending that may sit on the books without earning its keep. It is not the number investors use when asking 'will AI make money'. It is the number borrowers face when asked 'can you repay what you borrowed'. The bond market putting a 15% yield on CoreWeave can be read as its provisional answer to that question.
One caution is that the three numbers carry different degrees of certainty. The CPI and the Gartner estimate are primary sources. CoreWeave's bond yield and the size of the stock drop are based on reports. Bond yields move with every trade, so 15% is a figure that 'traded there at some point that day', not a fixed level.
What gets priced next
If the constraint on capital has become a market price, the next thing to watch is the terms facing borrowers raising money right now. The final terms of Volta's $5 billion loan, how Oracle's construction debt sells, the terms of Tencent's $5 billion bond, and the rates at which OpenAI's $1.4 trillion and SpaceX's $40 billion raises get done.
The same October 14 was also Anthropic's investor day. The July-to-September figures and how revenue through cloud channels is counted remain open questions from prior reporting. Whether labs and investors answer the criticism from Zitron and Marcus of how 'annualized revenue' is counted is also material for gauging borrowers' ability to repay, and the bond market has effectively started answering first.
Rates do not fall, bond buyers demand 15% from borrowers, Fink says 'new vehicles are needed', and Gartner counts the possibility of $3.5 trillion in impairment. That all four lined up on the same day is what gives this day its meaning. The view that what stops AI capital spending is not technology or power but whether the money can be borrowed has turned from words into a price.
Editorial cartoon
Sources
- https://www.bls.gov/news.release/cpi.nr0.htm
- https://www.cnbc.com/2026/10/14/us-treasury-yields-cpi-inflation-report.html
- https://cryptobriefing.com/coreweave-shares-plunge-bond-yields-15/
- https://www.gurufocus.com/news/9123604/coreweave-stocks-fall-over-15-as-debt-selloff-highlights-ais-interest-burden
- https://marketsmedia.com/blackrock-sees-large-opportunity-in-developing-compute-market
- https://pitchbook.com/news/articles/volta-launches-5b-leveraged-loan-package-to-support-data-center-lease-gpu-capital-expenditures
- https://www.gartner.com/en/newsroom/press-releases/2026-10-14-gartner-says-over-us-dollars-three-and-a-half-trillion-of-artificial-intelligence-infrastructure-spending-could-be-exposed-to-impairment-by-the-end-of-2030