Money · Oct 25, 2026
AI credit tightens and bridge debt grows: Nebius gets a 364-day, $3.5 billion loan from Citi, Marvell and TeraWulf expand credit lines, and CoreWeave's price target is cut to $70
After Meta's earnings, the price of AI debt has risen, and neoclouds and chipmakers are getting by on funding due within a year. SEC filings show multi-year contracts backed by short-term borrowing
Koji Yamamoto · Economics Analyst
Key points
- After Meta's earnings, a measure of the company's credit risk reportedly rose to a record high. Reliance on debt to fund AI capital spending has begun to show up in the price of credit
- Nebius disclosed to the SEC that it had obtained a 364-day, $3.5 billion bridge loan from Citi. Marvell and TeraWulf also filed notices of expanded credit facilities
- Morgan Stanley reportedly cut its CoreWeave price target to $70, citing financing concerns. The risk of backing long contracts with short-term debt is now feeding into how analysts value the stocks
The money flowing into AI data centers is changing. After Meta's earnings, a measure of the company's credit risk climbed to a record high, Investing.com reported. Around the same time, a string of neocloud and chip companies disclosed new financing arrangements to the SEC. Nebius obtained a 364-day, $3.5 billion bridge loan from Citi. Marvell and TeraWulf expanded their credit facilities. Morgan Stanley has reportedly cut its price target on CoreWeave to $70, citing financing concerns.
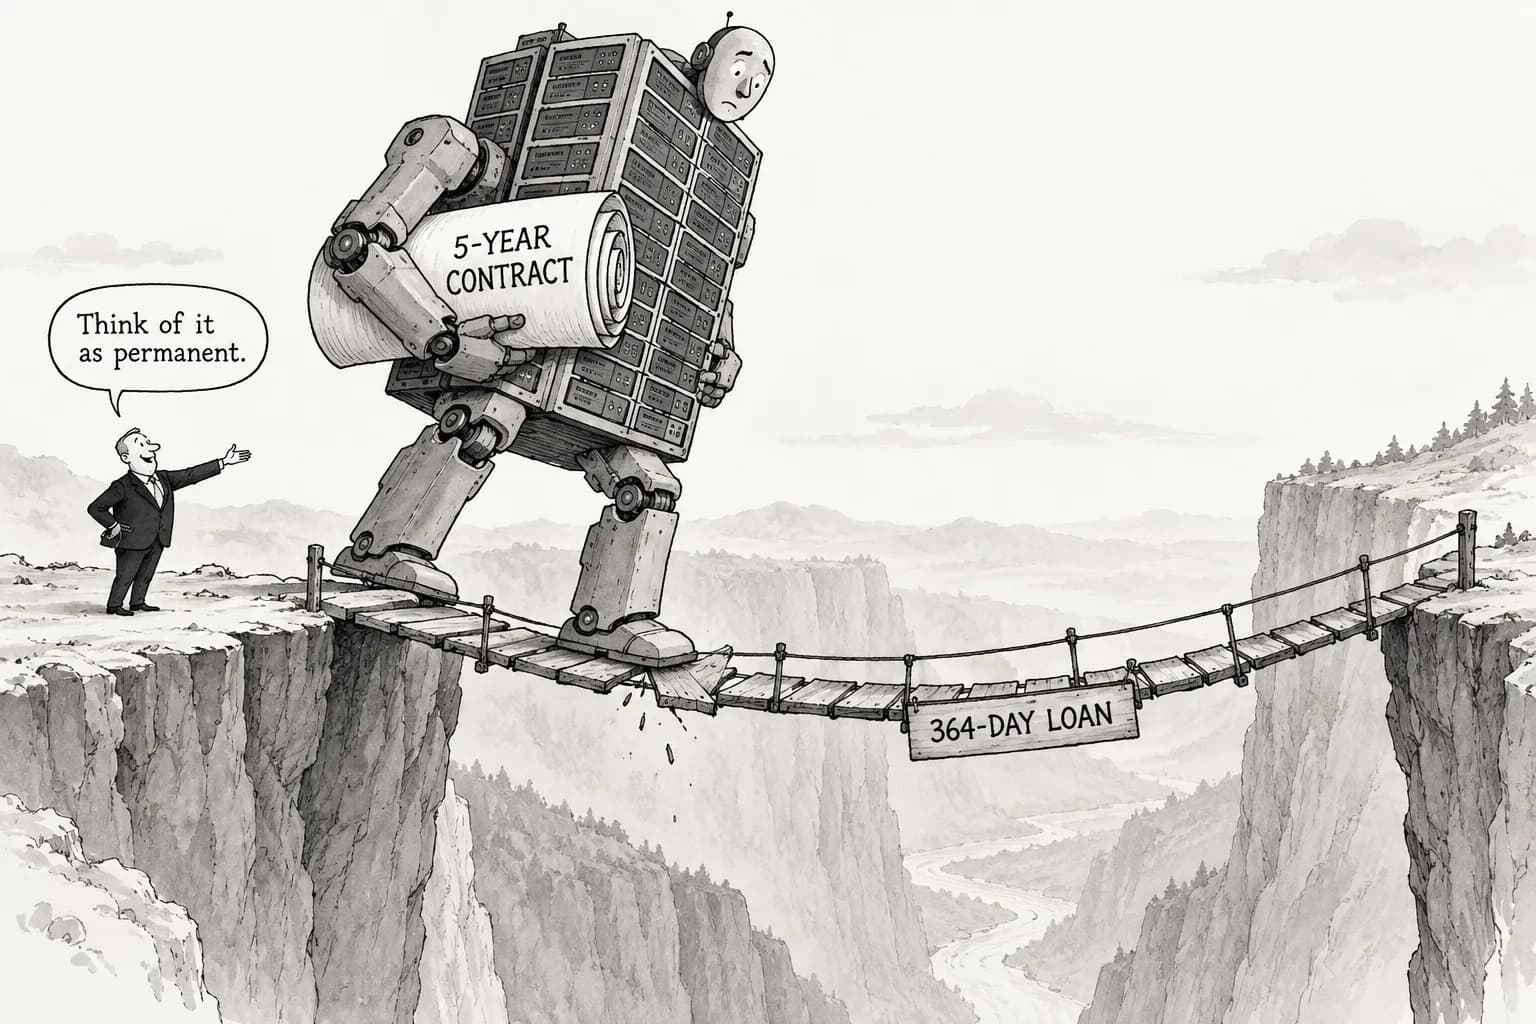
In each case, compute contracts and construction projects that run for years are being funded with debt due in roughly a year. The mismatch between long commitments and short funding goes largely unnoticed while credit is loose. When credit tightens, every refinancing forces a renegotiation of terms.
The trigger: Meta's credit got more expensive
According to Investing.com, a measure of Meta's credit risk rose to a record high after the company's earnings. Meta has sharply increased its AI-related capital spending. As Nohumans has previously reported, its off-balance-sheet commitments are estimated at about $825 billion, and a Class C share offering has also been floated. The market's view is that Meta is filling the gap beyond what its cash on hand can cover with debt and off-balance-sheet structures.
Meta is one of the buyers that generate AI demand at the very top of the chain. When the price of its credit rises, the effect quickly reaches the downstream companies that sign contracts with hyperscalers such as Meta and build facilities for them. The filings from the three companies below can be read as moves by those on the receiving end of that ripple.
Nebius: $3.5 billion for 364 days from Citi
Nebius disclosed in a filing with the SEC (Exhibit 99.1 to Form 6-K) that it had obtained a $3.5 billion loan from Citi. The term is 364 days.
The 364-day term matters. Loans of less than a year carry a lighter capital burden for the lending bank and are quicker to arrange. In exchange, the borrower must refinance within a year through bonds, equity or longer-term loans. In other words, this is a "bridge" until permanent financing is lined up.
Nebius signs multi-year compute contracts with large customers and is buying data centers and GPUs to match. The contracts run for years, the loan for less than one, and the gap is closed by refinancing within a year. If credit has tightened further by the time it refinances, the terms will be worse than they are now.
Marvell and TeraWulf: expanding credit lines
Chipmaker Marvell also disclosed in a Form 8-K that it had expanded its credit facility. Marvell makes custom chips for hyperscalers and networking components for data centers. The more its customers spend on capital projects, the more cash it needs for inventory and manufacturing prepayments. A credit facility is held as "insurance" to draw on when needed, and expanding it signals that the company expects more situations requiring cash.
TeraWulf, which has shifted its focus from bitcoin mining to AI data centers, also disclosed an expanded credit facility in a Form 8-K dated October 23. TeraWulf builds data centers on the basis of long-term lease contracts. Money goes out first for buildings and power infrastructure, while rent comes in over many years afterward. The expanded credit facility will bridge that gap.
Both filings take the same form: an expanded facility. Rather than issuing new long-term bonds, the companies bulked up arrangements that let them draw on bank funds as needed. At separate points in the AI supply chain, from chips to data centers, the same kind of measure appeared at the same time.
CoreWeave: what the $70 price target signals
Morgan Stanley is the one that factored this funding mismatch into its view of a stock. According to Investing.com, Morgan Stanley cut its price target on CoreWeave to $70, citing financing concerns.
CoreWeave has relied on debt more than any other neocloud. By the figures Nohumans has been tracking, the yield on its bonds maturing in 2031 has risen to about 15.97%, and its CDS to about 1,115bp. Even with revenue visibility, if the cost of borrowing to buy equipment rises, less is left for shareholders. What makes this price target cut significant is that it was based on the cost of funding, not on demand.
The gap between long contracts and short debt
Put the three filings next to CoreWeave's price target and a single pattern emerges. AI compute contracts are signed for multiple years. Yet the funding of the companies fulfilling them increasingly consists of short-term instruments, such as 364-day bridge loans and credit facilities drawn as needed.
This structure works only as long as there are lenders at every refinancing and the terms do not deteriorate sharply. When the price of credit rises for top-of-the-chain buyers such as Meta, that premise starts to wobble. If credit tightens upstream, downstream companies get squeezed on refinancing terms.
Next week brings earnings from Alphabet and Microsoft (October 28) and Amazon (October 29). Whether hyperscalers' free cash flow falls and their debt rises will set the conditions for what Nebius refinances its 364-day loan into, and how far CoreWeave's bond yields climb. Whether bridge debt stays a bridge depends on credit upstream.
Editorial cartoon
Sources
- https://www.sec.gov/Archives/edgar/data/1513845/000110465926117978/tm2628078d1_ex99-1.htm
- https://www.sec.gov/Archives/edgar/data/1835632/000119312526430424/d147430d8k.htm
- https://www.sec.gov/Archives/edgar/data/1083301/000162828026067100/wulf-20261023.htm
- https://ca.investing.com/news/stock-market-news/morgan-stanley-cuts-coreweave-stock-price-target-on-financing-concerns-93CH-4899282
- https://www.investing.com/news/economy-news/metas-credit-risk-indicator-jumps-to-record-high-after-results-4966556